If you have ever walked out of a property visit thinking, “This looks perfect,” and later wondered, “But will it actually make money?” you are not alone.
Real estate decisions in India often hinge on emotion rather than math. The broker will talk about “high demand,” your friend will talk about “this area is booming,” and someone will definitely say “property never fails.”
The truth is simpler. A property is a business. And like any business, it needs a clear way to estimate income, costs, taxes, and what you can realistically sell it for later.
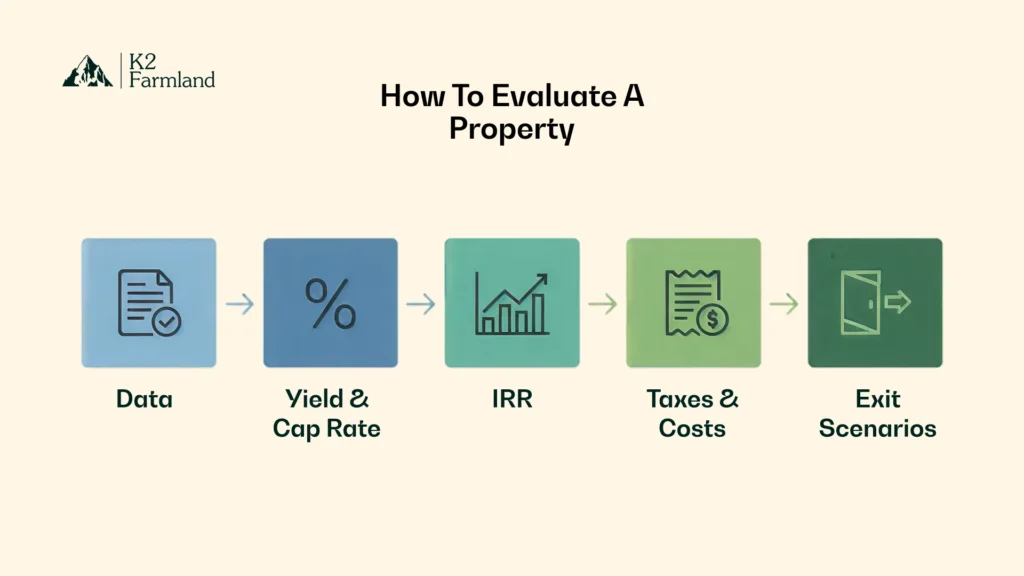
This guide gives you a conversational, step-by-step framework for evaluating real estate investments in India using rental yield, cap rate, IRR, taxes, and exit scenarios, without turning it into a finance textbook.
Start With A Simple Question: What Return Do You Want
Before numbers, get your target clear. Otherwise, you will keep adjusting assumptions until the deal “works.”
Ask yourself:
- Are you buying for steady rental income, long-term appreciation, or a mix
- How long will you actually hold it, three years, five years, ten years
- Are you buying with a home loan, partial loan, or all cash
- How much hassle are you willing to handle, tenant calls, repairs, vacancy, paperwork
- What is your minimum acceptable annualised return, after tax
This matters because rental yield and cap rate mostly tell you “how it looks today.” IRR tells you “how it performs over time.”
If you want a disciplined mindset, think of how operator-led asset managers evaluate real assets. K2’s approach, for example, focuses on disciplined evaluation and measurable performance, even though its core assets are farmland rather than apartments. The thinking is the same: you underwrite the downside, then you decide.
The Data You Need Before You Calculate Anything
Most mistakes happen because people start calculating with weak inputs.
Here is what you need, and why it matters.
Purchase And Setup Costs
These change your “true cost” immediately:
- Purchase price
- Stamp duty and registration (varies by state and buyer category)
- Brokerage and legal fees
- Interiors, furnishing, appliances
- Immediate repairs and upgrades
- Utility connection, society transfer charges, move in costs
If you ignore these, your yield and IRR will look better than they actually are.
Income Inputs
Get realistic here:
- Market rent, not “broker rent.”
- Expected vacancy, even good properties go empty sometimes
- Escalation terms, what do renewals actually look like in that building
- If commercial, lease terms, lock-in, escalation clauses, and fit-out responsibility
Operating Costs
These decide your net income:
- Society maintenance or CAM
- Property tax and municipal charges
- Insurance
- Repairs, reserve, paint, plumbing, appliance replacement
- Property management fee if you live elsewhere
Financing Inputs (If You Use A Loan)
Financing is where returns can swing sharply:
- Loan amount, interest rate, tenure
- EMI
- Prepayment plan
- Whether you can handle EMI during the vacancy
Exit Inputs
This is the part people skip, then regret later:
- Expected resale price range
- Selling costs
- Time to sell
- Capital gains tax assumptions
Rental Yield In India: Gross, Net, And Post Tax
Rental yield is your first filter. It is not your final decision, but it quickly tells you whether the property is an income-producing asset or mainly an appreciation bet.
Gross Rental Yield
Gross Rental Yield = Annual Rent ÷ Purchase Price
Example:
If rent is ₹35,000 per month, the annual rent is ₹4,20,000.
If the purchase price is ₹1,00,00,000, the gross yield is 4.2 percent.
This number is easy, and also dangerously optimistic.
Net Rental Yield
Net Rental Yield = (Annual Rent Minus Annual Operating Costs) ÷ Total Acquisition Cost
Total acquisition cost includes stamp duty, registration, brokerage, legal, and setup costs.
Let’s run a realistic example.
Assume:
- Purchase price: ₹1,00,00,000
- Stamp duty and registration plus misc purchase costs: ₹8,00,000 (illustrative, varies by state)
- Brokerage and legal: ₹1,00,000
- Interiors: ₹2,00,000
Total acquisition cost: ₹1,11,00,000
Rent side:
- Monthly rent: ₹35,000
- Vacancy: 1 month per year
Actual annual rent received: ₹35,000 × 11 = ₹3,85,000
Annual operating costs (illustrative):
- Maintenance: ₹36,000
- Property tax: ₹12,000
- Insurance: ₹5,000
- Repairs reserve: ₹10,000
Total operating costs: ₹63,000
Net operating income from rent: ₹3,85,000 minus ₹63,000 = ₹3,22,000
Net rental yield: ₹3,22,000 ÷ ₹1,11,00,000 ≈ 2.9 percent
That is why you should always compute net yield, not just gross yield.
Post Tax Yield (Quick Way To Think About It)
Post-tax yield depends on your tax slab and deductions, but the big idea is simple: rental income tax can reduce your take-home yield.
Rental income is generally taxed under “Income from house property.” Two common components that matter in your model are:
- 30 percent standard deduction on Net Annual Value
- Interest on borrowed capital deduction under Section 24(b), subject to applicable rules
If you are not modelling taxes at all, you are not modelling the deal.
Cap Rate: The Clean Comparison Metric
Cap rate is basically net yield expressed in a standard way.
Cap Rate = Net Operating Income (NOI) ÷ Current Market Value
NOI means income after operating expenses, but before loan EMI and before income tax.
Using our example:
NOI = ₹3,22,000
Value basis = ₹1,11,00,000
Cap rate ≈ 2.9 percent
Why cap rate useful?
- It helps compare two properties in different areas
- It helps compare residential vs commercial, because commercial often prices closer to the NOI logic
- It pushes you to focus on expenses and vacancy, not just headline rent
What cap rate does not tell you:
- What your loan does to your cash flows
- What taxes do to your return
- What happens at exit
So cap rate is a filter, not the full answer.
IRR: The Metric That Shows The Whole Journey
If you want one number that reflects the full story, IRR is as close as you get.
IRR is the annualised return that considers:
- Your upfront cash outflow
- Your yearly net cash flows
- Your sale proceeds at exit
- Your taxes and transaction costs
It is how serious investors compare opportunities across assets.
The Two IRRs You Should Know
- Unlevered IRR
This assumes no loan. It reflects the property’s performance as an asset. - Levered IRR (Equity IRR)
This includes your loan cash flows and tells you what your own invested money earned.
A deal can look “great” on levered IRR if you use high leverage, but it can also become fragile quickly if rent dips or EMIs rise.
A Simple IRR Walkthrough (Illustrative)
Let’s keep it clean.
Assume:
- Total acquisition cost: ₹1,11,00,000
- You put 30 percent down as equity: ₹33,30,000
- You take a loan for the rest: ₹77,70,000
- Net rent after operating costs: ₹3,22,000 per year (from earlier)
Now add two realities:
- EMI outflow each year (depends on rate and tenure)
- Rental income tax impact (depends on your personal slab and deductions)
Your equity cash flows look like this conceptually:
- Year 0: negative ₹33,30,000
- Year 1 to Year N: net rent after expenses minus EMI and minus tax
- Exit year: sale proceeds minus selling costs minus outstanding loan minus capital gains tax
Once you line these up in a spreadsheet, IRR becomes a button click.
The point is not to predict perfectly. The point is to model honestly.
Taxes And Transaction Costs You Must Include
This is where many “good deals” quietly become average deals.
Stamp Duty And Registration
Stamp duty is a state tax that varies widely. Registration charges and other fees can also apply. A useful rule is to treat these as part of the acquisition cost because they directly reduce your effective return.
TDS On Property Purchase (Section 194-IA)
If you are buying immovable property other than agricultural land, Section 194-IA generally requires TDS deduction when the consideration and stamp duty value meet the threshold conditions mentioned by the Income Tax Department.
This affects compliance and payment flow, and it is better to plan it upfront than scramble during registration.
Rental Income Tax Basics
Rental income is taxed under “Income from house property,” and the Income Tax Department explains common deductions such as:
- 30 percent standard deduction under Section 24(a)
- Interest on borrowed capital under Section 24(b), subject to rules
So when you evaluate yield, try to sanity-check a post-tax version too, even if it’s rough.
Capital Gains Tax And Holding Period
For immovable property such as land or buildings, the Income Tax Department’s capital gains tutorial notes a 24 month holding period test for long term classification.
It also notes changes in indexation treatment for transfers on or after 23 July 2024, and describes grandfathering for certain cases involving resident individuals or HUFs for land or buildings acquired before 23 July 2024.
Because tax outcomes depend on your dates, residency, and specifics, treat this as a modelling item you confirm, not an assumption you ignore.
Exit Scenarios: Where Most People Get Tricked
Most buyers spend 90 percent of their energy on buying, and 10 percent on exiting.
That is backwards.
Your exit decides your IRR.
Here are three exit scenarios you should model.
Base Case Exit
- Normal rent growth
- Normal vacancy
- Sale at a reasonable market price
- Normal selling costs
Downside Exit
- Slower resale market
- Sale price haircut
- More vacancy
- Higher repairs in later years
A simple way to think about resale risk is this: if buyers demand a higher yield in the market, prices can fall because income remains the same while the required return rises. This is why exit assumptions must be stress tested.
Upside Exit
- Faster demand in the micro market
- Stronger rent growth
- Better resale liquidity
Upside is nice, but never buy only because of upside.
Here is a quick scenario table you can use:
| Assumption | Downside | Base | Upside |
| Vacancy | 2 to 3 months | 1 month | near zero |
| Rent Growth | low | moderate | strong |
| Expenses | higher | normal | lower |
| Sale Price | discounted | fair | premium |
| Time To Sell | longer | normal | faster |
Stress Testing: A Quick Reality Check
Stress testing is the fastest way to spot a fragile deal.
Take your base case and apply four small shocks:
- Add 1 extra vacant month each year
- Reduce the rent growth assumption
- Increase repairs reserve by 20 to 30 percent
- Cut your expected exit price by 10 to 15 percent
If the deal falls apart under mild stress, it is not necessarily “bad,” but it is higher risk than it looks.
Due Diligence That Protects Your Return
Good underwriting is not only math. It is also risk control.
Title And Documentation
Always verify ownership, encumbrances, and documentation. If something feels unclear, treat it as a real risk, not as a “paperwork issue.”
RERA Checks For Under Construction Projects
RERA’s objective, as described by the Ministry of Housing and Urban Affairs, is to regulate and promote the real estate sector efficiently and transparently, and to protect homebuyers.
The Act also includes requirements for registering projects and agents.
Practically, you can verify registrations on state RERA portals. For example, UP RERA provides a public “Verify Rera Registration” tool.
If you are using an agent, recent advisories from state authorities also emphasise the importance of dealing with registered agents to reduce risk.
Why This Fits K2’s Style Of Thinking
K2’s philosophy is built around disciplined evaluation, operational control, and reporting. You can see an operator-led mindset across their Invest page, Impact framework, and case studies.
Even if you are evaluating an apartment and not farmland, the same discipline applies: clean diligence, realistic cash flows, stress-tested exits.
A Practical Approach You Can Try
If you want a simple underwriting sheet, start with this structure:
- Total acquisition cost = price + stamp duty + registration + brokerage + setup
- Annual rent received = monthly rent × (12 minus vacancy months)
- NOI = annual rent received minus annual operating costs
- Net yield = NOI ÷ total acquisition cost
- Cap rate = NOI ÷ current market value
- Build cash flows: Year 0 negative, Year 1 to N net, exit year sale proceeds net
- Add loan cash flows if financed
- Add rental income tax estimate using the house property deduction structure as a guide
- Add capital gains tax logic based on holding period and current rules
- Compute IRR for base, downside, upside
If you do just this, you will already be ahead of most buyers.
FAQs
What Is A Good Rental Yield In India
It depends on the city, micro market, property type, and vacancy risk. Use net yield as your baseline, then check if it still looks acceptable after tax.
Is Cap Rate More Important Than Rental Yield
Cap rate is generally cleaner because it uses NOI, which forces you to account for expenses. Rental yield is a fine first step, but it is often quoted on a gross basis, which can be misleading.
Why Should I Use IRR Instead Of Only Yield
Yield tells you “today.” IRR tells you “the full journey,” including purchase costs, yearly cash flows, and exit proceeds.
How Is Rental Income Taxed In India
Rental income is typically taxed under “Income from house property,” with common deductions including the 30 percent standard deduction and the interest deduction rules under Section 24, subject to applicable limitations.
When Does TDS Apply to Property Purchase
The Income Tax Department explains the conditions under Section 194-IA for TDS on the purchase of immovable property other than agricultural land, including the threshold conditions linked to the consideration and stamp duty value.
What Should I Check Under RERA
Confirm the project is registered on the relevant state RERA portal, review disclosures, and prefer working with registered agents, as RERA is designed to improve transparency and buyer protection.
Conclusion
A property investment feels easier when you stop chasing one “magic metric” and instead follow a simple flow: income, costs, taxes, and exit.
Key takeaways:
- Always calculate net rental yield, not just gross, because vacancy and expenses are unavoidable.
- Use the cap rate to compare properties using NOI, but do not treat it as the final decision.
- Use IRR for the full picture, especially if you are using a loan or planning a multi-year hold.
- Model India-specific frictions like stamp duty, registration, and TDS compliance, not as footnotes, but as real cash flows.
- Treat taxes as part of the model; rental income deductions and capital gains rules can change your take-home return.
- Do not skip exit scenarios; your resale assumptions often decide your IRR.
- Protect your downside with diligence, especially by conducting RERA checks for under-construction projects and verifying agent registration.